By Peter Catalano, ChFC®, CLU® | Catalano Financial
Buying a home is one of the largest financial decisions most people will make. Yet the conversation often begins with a simple question:
How much house can I afford?
After more than 30 years helping people make financial decisions, I’ve learned that there’s another question worth asking:
How much house makes sense for the life I’m trying to build?
Those are two very different questions.
A lender may determine that you qualify for a particular mortgage amount. A real estate professional can help you find a home that fits your needs and negotiate the purchase. But neither number, by itself, tells you how that decision fits into your retirement plans, investment strategy, cash reserves, or long-term financial goals. That’s where a comprehensive financial plan can help bring those decisions together.
That’s why I believe homeownership decisions benefit from collaboration.
Three Perspectives. One Important Decision.
At Catalano Financial, I value working alongside other professionals who bring their own expertise to a client’s financial decisions.
Two professionals I’m pleased to collaborate with are Sarah Messer, a real estate professional with Make Moves with Messer, and Karami Thomas, who works in mortgage financing.
Each of us approaches the home-buying process from a different perspective.
Sarah Messer — The Real Estate Perspective
Sarah helps buyers and sellers navigate the real estate market, evaluate properties, and understand the practical considerations involved in purchasing or selling a home.
Whether someone is buying their first home, relocating, upgrading, or downsizing, her role is to help them make informed real estate decisions.
Karami Thomas — The Mortgage Financing Perspective
Mortgage financing involves more than finding an interest rate.
Loan structure, down payment requirements, monthly obligations, closing costs, and available financing options can all influence a buyer’s financial flexibility.
Karami helps clients explore the mortgage side of the transaction and understand their financing options.
Peter Catalano — The Financial Planning Perspective
My role is to help clients consider how the home fits into their broader financial lives.
That may include evaluating cash reserves, retirement savings, investment allocations, future income needs, and the financial trade-offs associated with homeownership.
Together, these perspectives can help buyers and sellers make more coordinated decisions.
Just Because You Can Afford It Doesn’t Mean You Should Buy It
This is one of the most important conversations I have with clients.
A household might qualify for a substantial mortgage, but that doesn’t automatically mean taking on the maximum payment is the best decision.
Consider what happens when a larger mortgage payment competes with other priorities:
- Building or maintaining an emergency reserve.
- Contributing to retirement accounts.
- Saving for children’s education.
- Investing in a business.
- Enjoying travel, family experiences, or other personal goals.
For business owners, a home purchase may also affect the cash available to support their company. That’s why I believe personal and business financial planning should be considered together. The right home isn’t necessarily the most expensive home someone can qualify to purchase.
It’s the home that fits both their lifestyle and their financial priorities.
Your Cash Reserves Matter
One area I pay particular attention to is liquidity.
Purchasing a home can require significant cash for the down payment, closing costs, moving expenses, furnishings, and unexpected repairs.
It’s possible to purchase a beautiful home and immediately feel financially constrained because too much available cash went into the transaction.
That’s why I encourage clients to consider what their cash position will look like after closing, not just whether they have enough to complete the purchase.
A thoughtful financial plan considers both the home you’re buying and the flexibility you want to preserve. At Catalano Financial, our Financial Road Map® helps identify your financial priorities, evaluate your current position, and determine which decisions deserve attention before making a major commitment.
Homeownership and Retirement Planning
For clients approaching retirement, the conversation can become even more important.
Should you pay off your mortgage before retiring?
Would downsizing free up resources to support your retirement income?
Does maintaining a larger home still fit your lifestyle?
Could purchasing a different property create additional financial obligations at a time when your income is changing?
There isn’t one correct answer for everyone.
A decision that makes sense for a young family building wealth may be very different from the right decision for someone preparing to retire.
The objective is to understand the trade-offs before making a major commitment. These decisions are an important part of retirement income planning, particularly when transitioning from earning a paycheck to relying on investments, Social Security, and other income sources.
When Professionals Collaborate, Clients Can See the Bigger Picture
A home purchase involves several interconnected decisions.
The property you choose influences your financing needs. Your financing structure affects your monthly cash flow. And your cash flow affects your ability to save, invest, and pursue other financial goals.
When your real estate professional, mortgage professional, and financial advisor communicate, you have an opportunity to evaluate those decisions together rather than separately.
That doesn’t mean every client needs three professionals involved in every conversation.
It means recognizing when coordination can lead to a more informed decision.
It’s About More Than the House
One of my favorite sayings is:
“It’s not about the money. It’s the emotion behind the money.”
A home represents far more than an asset on a balance sheet.
It can represent security, family, accomplishment, stability, or the beginning of a new chapter.
Understanding those motivations is just as important as understanding the numbers.
Whether you’re purchasing your first home, considering an upgrade, relocating, or preparing to downsize in retirement, I encourage you to look beyond the transaction.
The goal isn’t simply to buy the house you can afford. It’s to make a housing decision that supports the life you want to live.
At Catalano Financial, that’s where financial planning begins.
Working Together for a Bigger Financial Picture
Buying or selling a home involves decisions that can affect your finances for years to come. Having professionals who understand different aspects of the process can help you make those decisions with greater clarity.
I’m pleased to collaborate with two professionals serving the Greater Houston and The Woodlands communities:
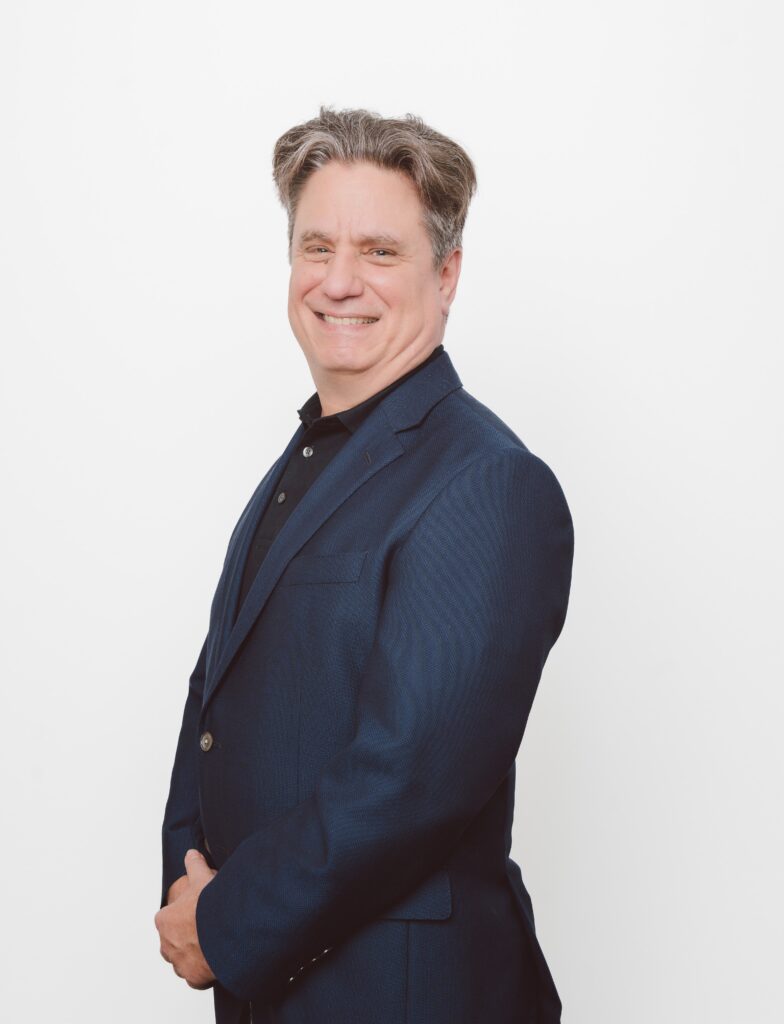
📊 Peter Catalano, ChFC®, CLU® — Catalano Financial
I help clients evaluate how buying, selling, or refinancing a home fits into their overall financial plan, including retirement planning, investment management, cash reserves, and long-term financial goals.
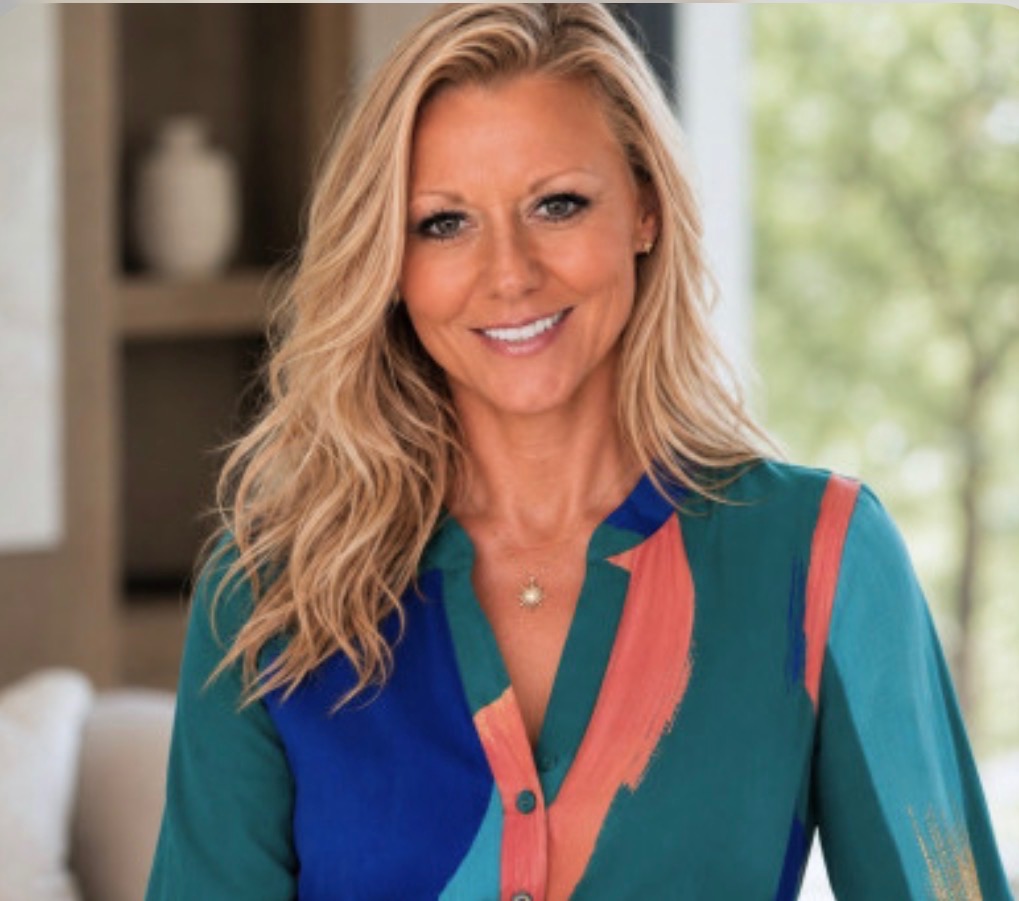
🏡 Sarah Messer — Make Moves with Messer | Top Guns Realty
Sarah helps individuals and families navigate buying, selling, relocating, and downsizing. Her real estate perspective helps clients evaluate their housing decisions and opportunities.
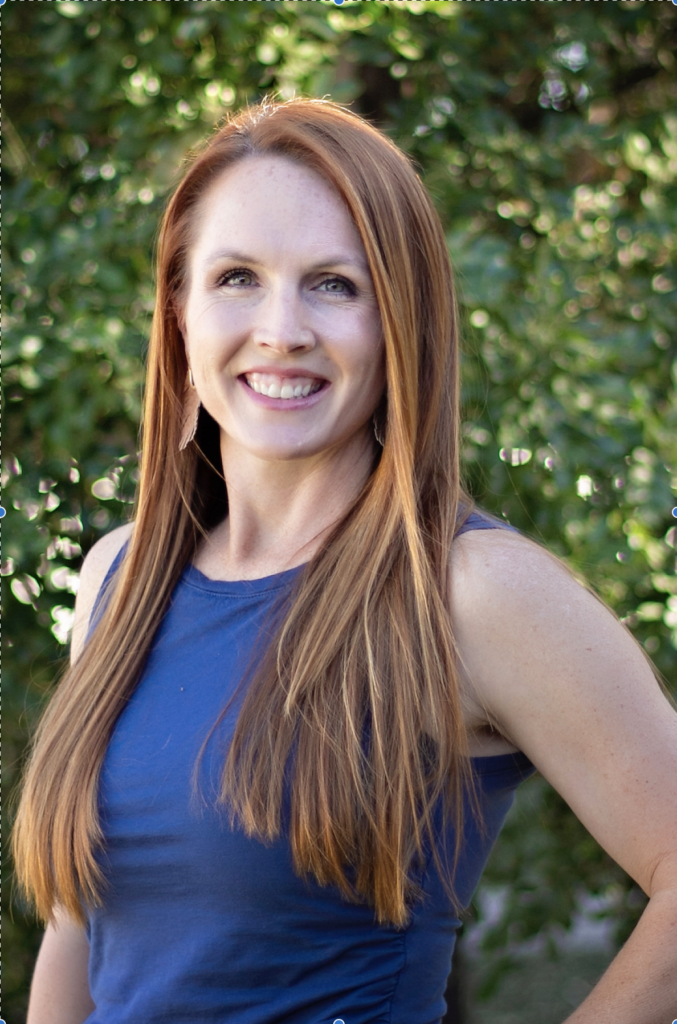
🏠 Karami Thomas — Mortgage Financing | Loan Factory
Karami helps homebuyers explore mortgage financing options, including loan structures, down payments, and financing considerations that influence affordability.
The Bigger Picture
Whether you’re buying your first home, moving into a larger property, or downsizing for retirement, the goal is the same:
Make a housing decision that supports the life you want to live.
That’s what thoughtful financial planning is all about