Indexed Universal Life (IUL) is permanent life insurance that pays a death benefit and grows a cash value tied to a market index, so it can protect your family and build money you can borrow against later. This page is for high net worth individuals and families in The Woodlands, TX who want tax-advantaged growth alongside real coverage. I’m with Catalano Financial, and I’ve been designing and placing life insurance for clients since 1992.
Key takeaways
- An IUL is permanent coverage: it stays in force for life when it’s funded properly, unlike term insurance.
- Its cash value grows based on the performance of a market index, most often the S&P 500, without being invested directly in the market.
- A cap rate limits your upside in a good year, and a floor rate (usually 0% or 1%) protects you when the index falls.
- Growth is tax-deferred, and you can access cash value through policy loans without triggering a taxable event when the policy stays in good standing.
- Some high net worth individuals use the cash value as collateral to fund real estate or other purchases while the policy keeps earning.
How does an indexed universal life policy build wealth?
An IUL builds wealth by crediting interest to your cash value based on how a market index performs, then letting that value compound tax-deferred year after year. It’s a type of permanent life insurance, so it remains in force for life as long as it’s funded correctly. Whole life ties growth to a fixed schedule, while an IUL ties growth to an index like the S&P 500.
Your money is not invested directly in the market. The insurance company uses the index’s performance to decide the interest credited to your policy, and two features shape that number:
- Cap rate. This is the most interest the policy can earn in a crediting period. If the cap is 10% and the index rises 14%, you’re credited 10%.
- Floor rate. This is the least you can earn, usually 0% or 1%. If the index drops, you don’t lose your principal or the gains you already locked in.
That design shields you from market losses while still giving you meaningful upside, and the compounding happens inside the policy where taxes aren’t taking a cut each year.
How do you get money out of an IUL?
You reach the cash value through policy loans, which can be taken tax-free as long as the policy stays in good standing. Because the growth is tax-deferred, you aren’t paying tax on the gains while they sit in the policy.
Three points make this attractive for people planning for retirement:
- Tax-deferred growth means no yearly tax bill on the interest credited.
- Tax-free access through loans means you can pull cash without creating a taxable event, provided the policy is managed well.
- No age 59½ rule and no required minimum distributions. Unlike a qualified retirement plan, you can take policy loans at any age with no early-withdrawal penalty.
Can you use an IUL to buy property or invest?
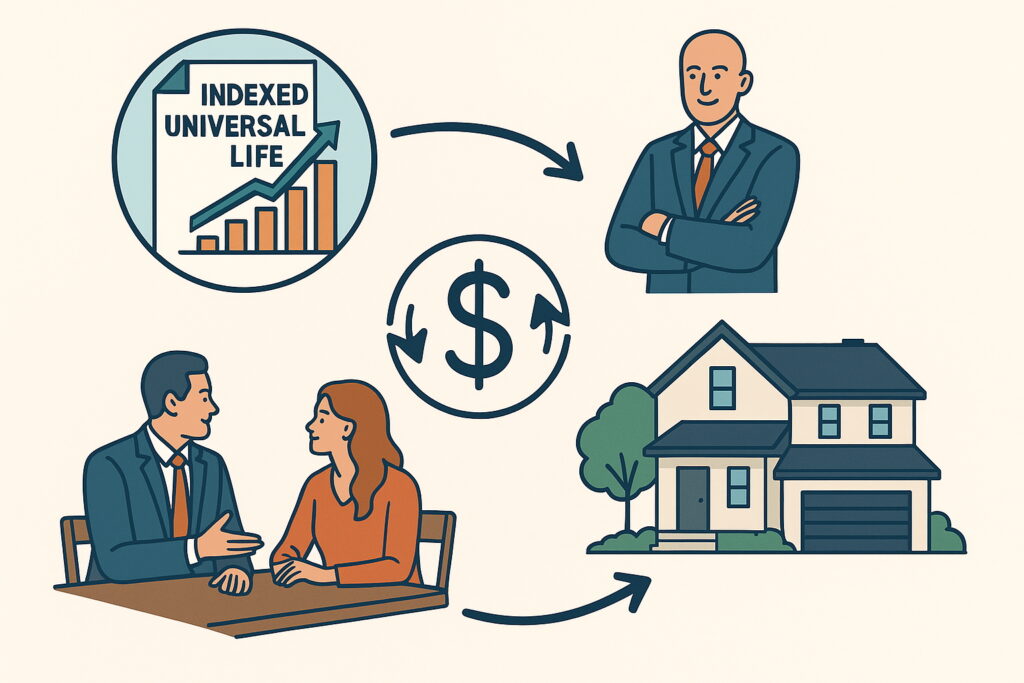
Yes. One advanced strategy uses your accumulated cash value as collateral, either by borrowing against the policy directly or by pledging it to a bank, so you can fund real estate or other assets without cashing out.
Here’s how it plays out in practice. Say you fund an IUL over 7 to 10 years and build $500,000 in cash value. Instead of withdrawing that money, which would reduce your death benefit and interrupt growth, you borrow against it. You use the loan as a down payment on an income-producing property while your policy value keeps earning interest, because it’s still intact. You repay the loan over time from rental income or other cash flow.
People sometimes call this a “Bank on Yourself” or “Infinite Banking” approach, because your dollars work in two places at once: earning inside the policy and invested in the property. For larger cases, this can pair with a lending arrangement covered on my premium financing strategy page.
A few things I always walk clients through before we go this route:
- Loan rates. Policy loans may carry fixed or variable interest, so we compare the cost of borrowing against your projected return.
- Policy design. Overfunded policies that minimize insurance cost and maximize cash value work best for leverage.
- Risk of lapse. If loans aren’t managed or the policy underperforms, it can lapse and create tax consequences.
- Liquidity timeline. It usually takes several years of funding before there’s enough cash value to make leveraging worthwhile.
What does an IUL cost and how do you pay?
The premium depends on your age, health, the coverage amount, and how much you want to overfund the policy for cash value, so there’s no single sticker price. Premiums are paid to the insurance carrier, and for a wealth-building design we usually plan a funding schedule over several years rather than a single payment.
I start every case with a free discovery call to understand your goals before quoting anything. If an IUL fits, I show you an illustration with the numbers behind it so you can see the projected cash value, the death benefit, and the cost of insurance side by side. If it doesn’t fit, I’ll tell you plainly and point you toward the types of life insurance that suit you better.
Why work with Catalano Financial?
I’ve been advising individuals and families since 1992, and I hold the CLU and ChFC designations, which focus on life insurance and advanced financial planning. I’m a Registered Investment Advisor in Texas and insurance licensed in both TX and CO, so I can look at your IUL as one piece of a full plan rather than a standalone sale.
An IUL only works when it’s designed and funded with discipline, and I stay involved after the policy is placed to keep the loan strategy and funding on track. One client used their IUL to help fund the build-out of storage units. The funds stayed in the IUL earning interest while a loan from the policy paid for construction. Now income flows from both the storage units and the policy’s cash value. It was powerful to watch that strategy work.
Where do you serve?
I work with high net worth individuals and families in The Woodlands, TX and the surrounding communities. Because I’m licensed for insurance in Texas, California and Colorado and a Registered Investment Advisor in Texas, I can serve clients in all three states.
How do I book?
Book a free discovery call at https://savvycal.com/catalanofinancial/discovery-call, or call me directly at 832-696-0990. You can also read more about my life insurance services before we talk.
Frequently asked questions
Is the cash value in an IUL guaranteed to grow every year?
No, growth isn’t guaranteed, but the floor rate protects you from losses. In a year the index is negative, most policies credit 0% or 1%, so you don’t lose principal or prior gains. In a strong year, your credit is limited by the cap rate, so you won’t capture the full index return.
How long before an IUL has enough cash value to borrow against?
It usually takes several years of consistent funding, often around 7 to 10 years, before the cash value is large enough for a leverage strategy to make sense. Overfunding the policy in the early years builds cash value faster. I’ll show you a projected timeline in your illustration before you commit.
Do I need to be wealthy to use an IUL?
An IUL can work for many individuals and families, but the leverage and property-purchase strategies described here fit high net worth individuals with the cash flow to fund the policy well. If a large IUL isn’t right for your situation, we’ll look at other options, and my page on common life insurance myths clears up a few points people often get wrong.
What happens to my IUL if I take loans and then pass away?
Any outstanding loan balance plus interest is subtracted from the death benefit, and your beneficiaries receive the rest. Keeping the policy in good standing matters, because an unpaid loan on an underperforming policy can cause a lapse and create tax consequences. I monitor funding and loan levels with clients to help avoid that.
Do you serve clients outside The Woodlands?
Yes. I’m based in The Woodlands, TX and I’m insurance licensed in Texas, California and Colorado, and a Registered Investment Advisor in Texas, so I work with clients across all states. Call 832-696-0990 to see whether I can help where you live.